March 4, 2026 · 8 min · Houston · Katy · Spring
A denial letter isn't always the end of the story. Carriers deny or underpay claims for a range of reasons, some of which are legitimate policy exclusions and some of which are worth pushing back on with better documentation. Here is how to figure out which situation you're in.
Common reasons roof claims get denied
Wear and tear or age-related deterioration
Homeowner policies cover sudden, accidental damage, not gradual deterioration. If an adjuster determines the roof failed due to age rather than a specific storm event, they will typically deny the claim on that basis. A roof nearing the end of its expected life is more likely to draw this determination even after a real storm.
Cosmetic hail damage exclusions
Some policies, particularly certain metal roof endorsements, include a cosmetic damage exclusion that denies claims for hail marks that dent or discolor a roof without affecting its function. Check your policy's endorsements page for this exact language, since it is not on every policy.
Late reporting
If you wait too long after a storm to file, many carriers will deny or heavily scrutinize the claim, since it becomes harder to confirm the damage matches that specific weather event. This is one of the most preventable denial reasons, which is why we recommend filing promptly once damage is confirmed.
Lack of maintenance
If an adjuster finds evidence of long-term neglect, like ongoing leaks that were never addressed, or moss and organic growth that suggests years of moisture intrusion, the carrier may argue the damage stems from lack of maintenance rather than a covered peril.
Step 1: Request the full adjuster report
You are entitled to a copy of the adjuster's inspection report and photos. Call your claims representative and ask for the complete file, not just the denial letter summary. This report tells you exactly what the adjuster saw and why they made their determination, and it's the starting point for any pushback.
Step 2: Get a second, independent roof inspection
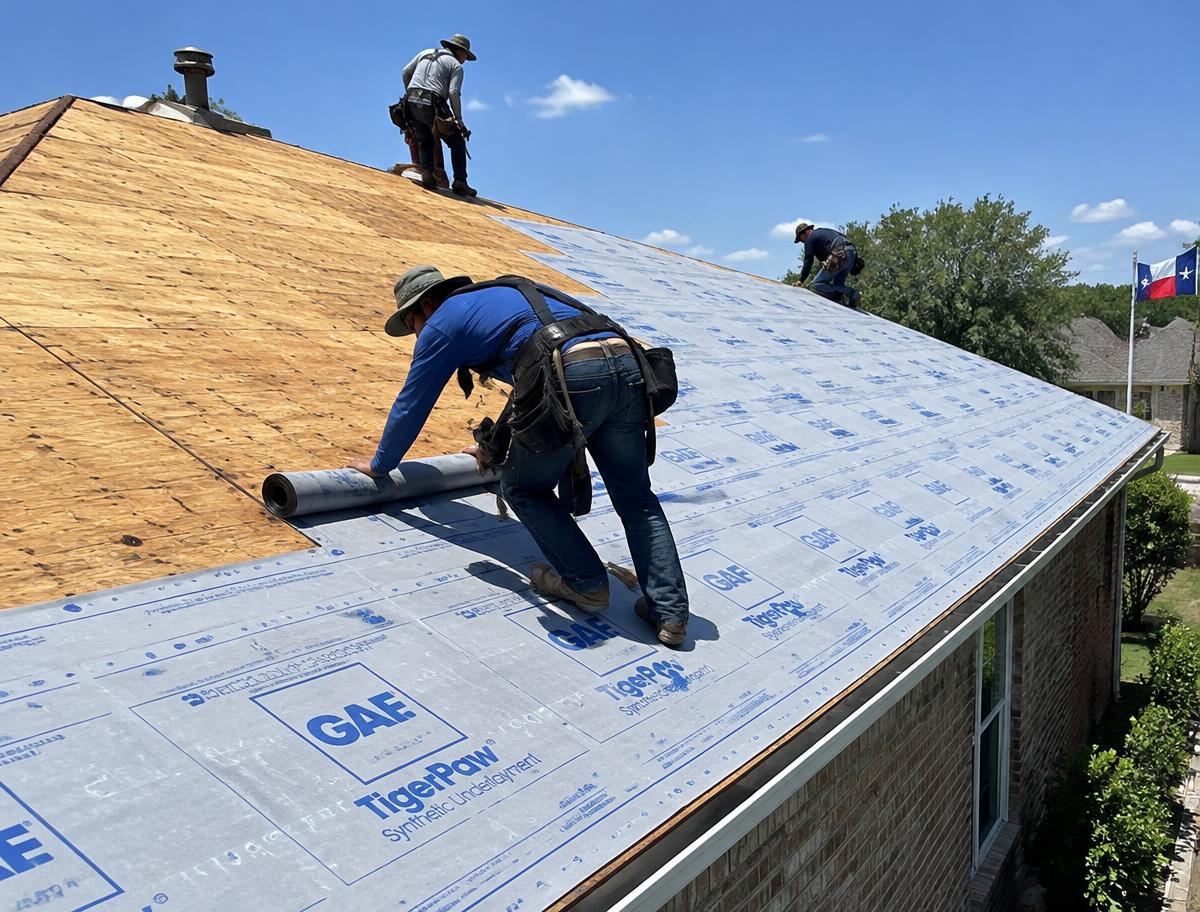
Have a local roofing contractor do a separate, thorough inspection and produce photo documentation of every slope. Compare that against the adjuster's report line by line. If the adjuster missed damage on a slope they didn't fully access, or misclassified storm damage as wear, this documentation is what supports a reinspection request.
Step 3: Request a reinspection
Most carriers allow you to request a second inspection, sometimes with a different adjuster or a re-review by a supervisor, when you can present new documentation. Submit your contractor's report and photos in writing and ask for a formal reinspection.
Step 4: Understand the appraisal clause
Many Texas homeowner policies include an appraisal clause, a built-in dispute process where you and the carrier each hire an independent appraiser, and the two appraisers select a neutral umpire if they disagree. This process resolves disagreements over the dollar amount of a covered loss, not whether something is covered at all. Read your policy's appraisal section or ask your agent whether it applies to your situation.
Step 5: Know when to bring in a public adjuster or attorney
A licensed public adjuster works for you, not the insurance company, and can handle negotiation and paperwork on your behalf for a fee, usually a percentage of the settlement. An attorney who handles property insurance disputes is another option if you believe the carrier is acting in bad faith. A roofing contractor, including us, cannot legally take on this negotiating role, but we can supply the documentation either professional will need.
What Redfish Roofing can and can't do
We can reinspect your roof, produce clear photo and video documentation, meet with an adjuster on a reinspection, and write up a scope of damage. We cannot argue policy interpretation, negotiate your settlement, or guarantee an outcome. Those limits exist to protect you as much as us.
Frequently asked questions
Can I appeal a denied roof claim in Texas?
Yes. You can request a reinspection, submit new documentation, and where applicable use your policy's appraisal clause. You can also file a complaint with the Texas Department of Insurance if you believe your claim was handled in bad faith.
How much does a public adjuster charge?
Public adjusters typically work on a percentage of the settlement, and fees vary by adjuster and state rules. Get the fee agreement in writing before signing anything.
What is the difference between reinspection and appraisal?
Reinspection is an informal second look, often by the same carrier, using new documentation. Appraisal is a formal, policy-defined process using independent appraisers and an umpire to resolve a dollar-amount dispute.
Does a denial mean I can't ever get the claim paid?
Not necessarily. Many denials are reversed after reinspection with stronger documentation. It depends on the specific reason for denial and what new evidence is available.
Will Redfish Roofing come out for a second inspection even if my first roofer isn't available?
Yes, we offer free inspections regardless of who did your original claim documentation, and we're happy to provide a written report you can submit for reinspection.